
When searching for the health insurance portability rules, understanding the underlying coverage details and policy mechanics is essential. In today’s volatile economic environment, securing robust medical financial protection protects your household against catastrophic out-of-pocket expenses. This detailed guide analyzes health insurance portability rules, switch health insurance company, retain no claim bonus portability, irdai insurance portability guidelines to help you make an informed decision.
Understanding Your Legal Right to Port Health Insurance Policies
Selecting the right health insurance policy requires evaluating deductible limits, co-insurance provisions, and network hospital availability. Prioritizing comprehensive coverage ensures that unexpected emergency ER visits, ICU charges, and specialist consultations are fully covered without causing personal financial strain.
Industry research shows that policyholders who thoroughly compare switch health insurance company save up to 30% on annual premiums while enjoying superior claim settlement speeds.
Comparison Table & Policy Breakdown
Review the comprehensive comparison matrix below to evaluate different plan tiers and cost structures for health insurance portability rules:
| Portability Stage | Timeframe Window | Action Required by Policyholder | Insurer Obligation |
|---|---|---|---|
| Notice Submission | 45 to 60 Days Before Renewal | Submit Portability Form & Renewal Notice | Acknowledge request within 3 days |
| Data Exchange | Within 7 Days of Notice | Provide past policy copy & claim history | Fetch credit details from insurance portal |
| Underwriting Decision | Within 15 Days of Data Fetch | Complete medical checkup if requested | Issue approval or counter-offer |
| Policy Transition | On Policy Renewal Date | Pay premium to new insurer | Issue new policy with continuous credit |
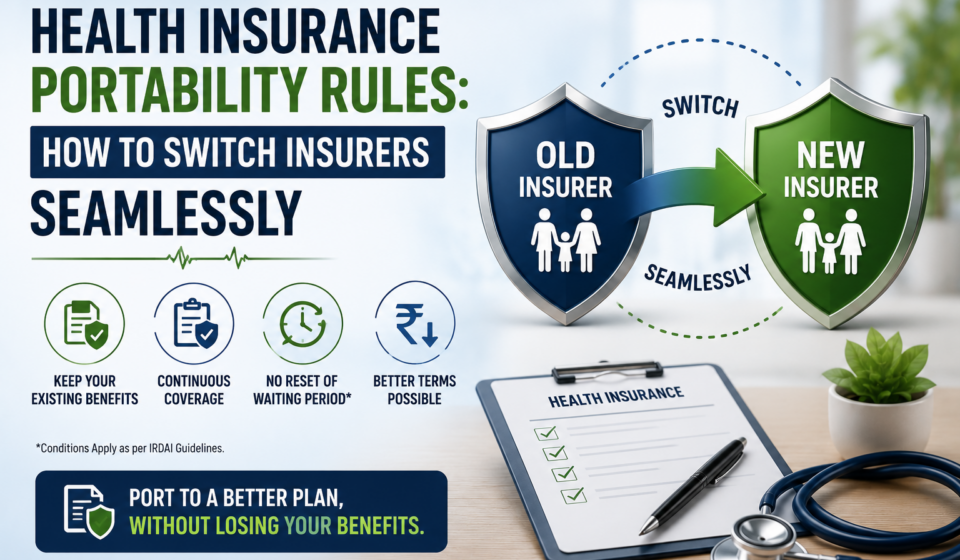
How Transferring Policies Preserves Waiting Periods and NCB Benefits
To maximize the value of your policy, consider these critical coverage features and policy benefits:
- Key Feature: Seamless transfer of accumulated waiting period credits for pre-existing diseases.
- Key Feature: Preservation of accrued No-Claim Bonus (NCB) sum insured increases.
- Key Feature: Freedom to switch from underperforming insurers with high claim rejection rates.
- Key Feature: No loss of coverage continuity or penalty fees for changing insurance carriers.
- Key Feature: Option to upgrade sum insured limits during the portability transition.
Step-by-Step Timeline and Documentation for Insurance Portability
Follow this step-by-step framework when purchasing or renewing your policy to ensure total compliance and maximum benefits:
- Initiate portability application at least 45 days prior to your current policy expiry date.
- Gather past policy schedules, claim payout statements, and medical discharge summaries.
- Fill out the standard Portability Form provided by your prospective new insurer.
- Undergo medical checkups if required based on age or sum insured upgrade requests.
- Pay the new premium upon underwriting approval to maintain continuous coverage.
Conclusion & Expert Recommendation
Securing a high-quality policy backed by top-rated health insurance providers guarantees peace of mind and long-term financial security. Always read the fine print regarding waiting periods, pre-existing disease riders, and cashless authorization protocols before finalizing your enrollment.