
When searching for the health insurance deductible, understanding the underlying coverage details and policy mechanics is essential. In today’s volatile economic environment, securing robust medical financial protection protects your household against catastrophic out-of-pocket expenses. This detailed guide analyzes health insurance deductible, co-pay in health insurance, out of pocket maximum, coinsurance health plan cost to help you make an informed decision.
Demystifying Cost-Sharing Terms in Medical Insurance
Selecting the right health insurance policy requires evaluating deductible limits, co-insurance provisions, and network hospital availability. Prioritizing comprehensive coverage ensures that unexpected emergency ER visits, ICU charges, and specialist consultations are fully covered without causing personal financial strain.
Industry research shows that policyholders who thoroughly compare co-pay in health insurance save up to 30% on annual premiums while enjoying superior claim settlement speeds.
Comparison Table & Policy Breakdown
Review the comprehensive comparison matrix below to evaluate different plan tiers and cost structures for health insurance deductible:
| Term Name | Definition / Function | When It Applies | Effect on Premium |
|---|---|---|---|
| Deductible | Fixed amount patient pays before policy begins paying | At beginning of annual policy cycle | Higher deductible = Lower premium |
| Co-Payment (Co-Pay) | Percentage of every hospital bill paid by policyholder | On every single claim submitted | Higher co-pay = Lower premium |
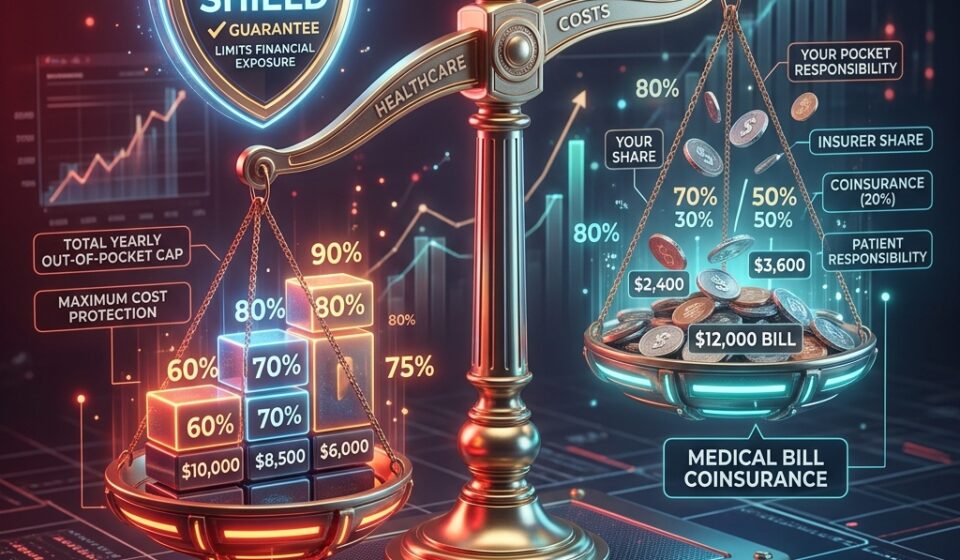
| Coinsurance | Percentage split between insurer and patient after deductible | Post-deductible until out-of-pocket max | Standard 80/20 or 90/10 split |
| Out-of-Pocket Maximum | Absolute ceiling on total yearly patient costs | Cap across all deductibles & coinsurance | Protects against financial ruin |
How Deductibles and Co-Pay Ratios Impact Your Annual Premium
To maximize the value of your policy, consider these critical coverage features and policy benefits:
- Key Feature: Deductibles must be met prior to insurance reimbursement for standard care.
- Key Feature: Out-of-pocket maximum caps protect policyholders from catastrophic medical bills.
- Key Feature: Co-payments are common in senior citizen plans and zone-based network coverage.
- Key Feature: In-network doctors offer negotiated fee discounts that lower coinsurance burdens.
- Key Feature: Preventive healthcare services are frequently exempt from deductibles under law.
Real-World Claims Calculation: Step-by-Step Breakdown
Follow this step-by-step framework when purchasing or renewing your policy to ensure total compliance and maximum benefits:
- Check your policy schedule for specific deductible and co-pay clause details.
- Calculate your financial capacity to pay upfront deductibles during health emergencies.
- Choose a zero co-pay plan if you prefer predictable, fixed health expenditure.
- Track medical bills throughout the calendar year to monitor progress toward out-of-pocket caps.
- Review claim statements (Explanation of Benefits) to verify proper cost-sharing application.
Conclusion & Expert Recommendation
Securing a high-quality policy backed by top-rated health insurance providers guarantees peace of mind and long-term financial security. Always read the fine print regarding waiting periods, pre-existing disease riders, and cashless authorization protocols before finalizing your enrollment.